Tanker sale and purchase carried the week’s largest numbers, dry bulk owners split between en bloc disposals and long-term newbuilding cover, and subcontinent recycling held firm while Turkey traded at a wide discount.
UAE buyers acting through Onex took the week’s largest crude fixture, the RAIN CUBIS, a 2008-built 319,429 dwt VLCC, at USD 91 million. The MONTESTENA, a 2012-built 159,372 dwt Samsung-built Suezmax, sold for USD 87 million. Chinese buyers acquired the XI XIU, a 2003-built 299,996 dwt unit, at USD 61 million, more than double the USD 31 million her sellers paid in February 2025, and the DENNIE, a 2000-built 308,491 dwt unit, sold to UAE buyers at USD 40 million, up from the USD 30 million paid for her in the summer of 2025.
Product tonnage moved further down the size range. Sister tankers MARLIN HERA and MARLIN HESTIA, 2017-built 74,000 dwt units from Sungdong, sold en bloc at USD 49 million each, and the OLYMPIC FLAG and OLYMPIC FUTURE, 2004-built 155,000 dwt sisters from Namura, each achieved USD 50 million.
Newbuilding cover extended across crude, product and gas tonnage. Dynacom contracted four 306,000 dwt tankers at Hengli in China at USD 123 million each for 2029 delivery, alongside two 158,000 dwt tankers at the same yard. Advantage Tankers contracted two 50,000 dwt MR2 product tankers at Guangzhou Shipyard International at USD 45 million each, and Akrotiri Tankers ordered two 93,000 cbm VLGCs at NTS at USD 110 million each. Dynagas placed the week’s largest gas order, four 200,000 cbm LNG carriers at Samsung at USD 262.5 million each, and added a further four LNG carriers at Samsung with the order reported at USD 1.1 billion in total.
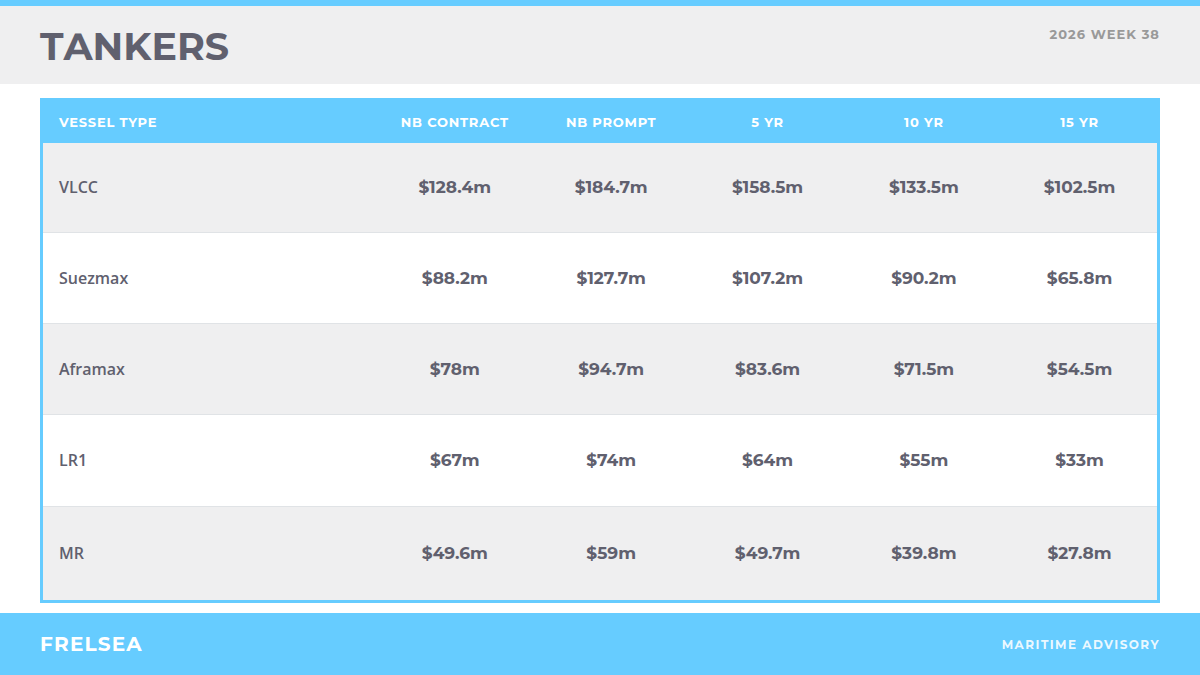
Price levels moved higher through the week. The VLCC ten-year mark rose to USD 133.5 million, extending a climb from USD 122.25 million five weeks earlier, and the Suezmax and Aframax curves firmed alongside it.
The week’s largest dry bulk fixture was en bloc. The HOUHENG 5 and HOUHENG 6, 2017-built 261,000 dwt sisters built in China, sold together at USD 70 million each. The BORA, a 2014-built 81,682 dwt unit, was rumoured committed to Greek buyers at a price in the region of USD 22.5 million, with her identical sister SIROCCO having sold at around USD 20 million back in May. The KING LOONG, a 2006-built 77,430 dwt unit from Oshima, sold to Chinese buyers at USD 13 million, and the HC WISDOM, a 2013-built 95,711 dwt Imabari unit, achieved USD 24.5 million.
Newbuilding activity brought a long-term structural driver into the sector. HMM contracted eight 210,000 dwt ore carriers at Yangzijiang Shipbuilding at USD 105 million each for 2030 delivery, with the order backed by 25-year contracts with the Brazilian mining company Vale. Turkish interests at GSD Holdings placed one 40,300 dwt bulk carrier at Nihon in Japan for 2030 delivery.
Further down the size range, the VELA, a 2007-built 53,565 dwt unit, sold at a price in the region of USD 10 million, close to the USD 11 million achieved by her sister BLUE DIAMOND in July. The IPSEA COLOSSUS, a 2011-built 58,818 dwt unit, was rumoured sold at USD 20.75 million. The INDIGO BREEZE, a 2017-built 60,430 dwt unit, sold to Greek buyers at USD 30.5 million, and the SIDER BELLEZZA, a 2026-built open hatch newbuilding of 40,010 dwt delivered from Naikai Zosen in Japan, changed hands at USD 38.5 million.
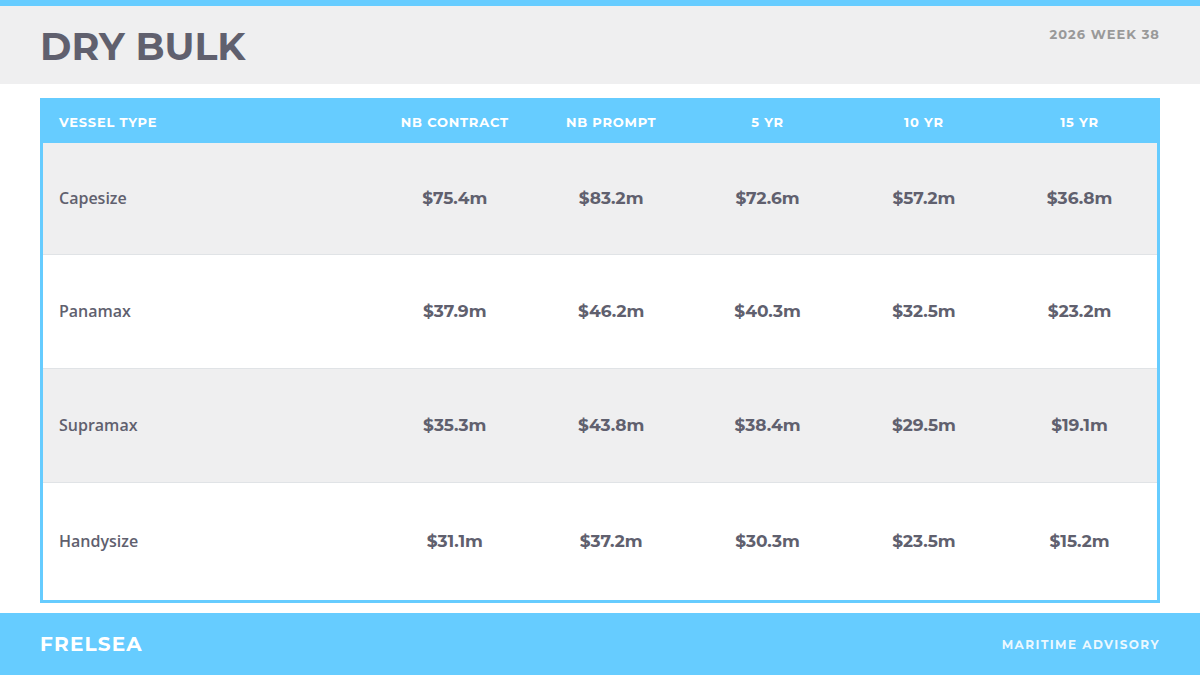
The Capesize ten-year mark has held close to USD 57 million for the past month, with Panamax and Supramax levels similarly settled across the age curve.
Prices held firm on light business. The MAESTRO 1, a 1998-built Japanese bulk carrier of 5,142 LDT, went to Pakistan at USD 507 per LDT. The LEO STAR, a 1992-built motortanker of 1,961 LDT, sold into Bangladesh at USD 485 per LDT. The SORMOVSKIY-123, a 1985-built general cargo ship of 1,053 LDT, went to Turkey at USD 260 per LDT. The DAYTONA-H, NOVAYA ZEMLYA, SPRING and SU RUI 169 also changed hands for recycling this week, on delivered or as-is terms, without a disclosed price.
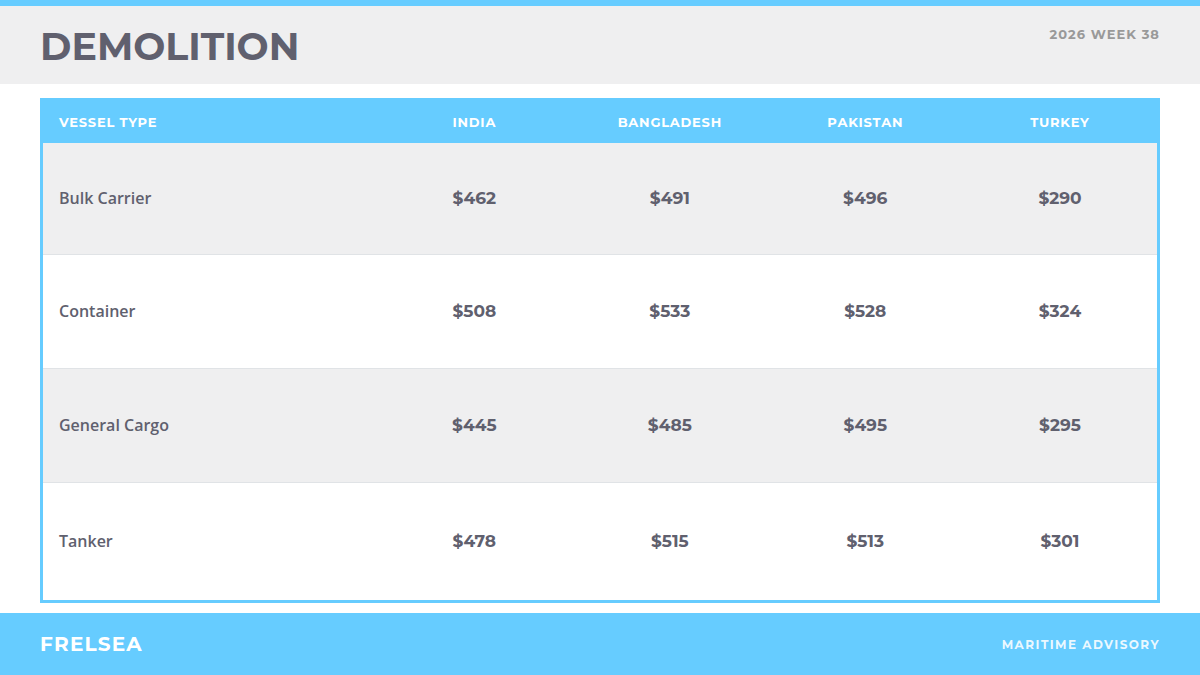
Levels across the Indian subcontinent stayed close together. India bid USD 478.16 per LDT for tankers and USD 462.20 for bulk carriers, Bangladesh USD 514.51 and USD 491.01, and Pakistan USD 513.20 and USD 495.96. Turkey remained the outlier at USD 300.83 for tankers and USD 289.58 for bulk carriers, a gap that has held for months and tracks the different cost base and domestic steel demand at Turkish plots.