Crude tankers dominated week 37, with seven VLCC sales reported alongside firm Kamsarmax buying and a recycling market that produced almost no fresh business.
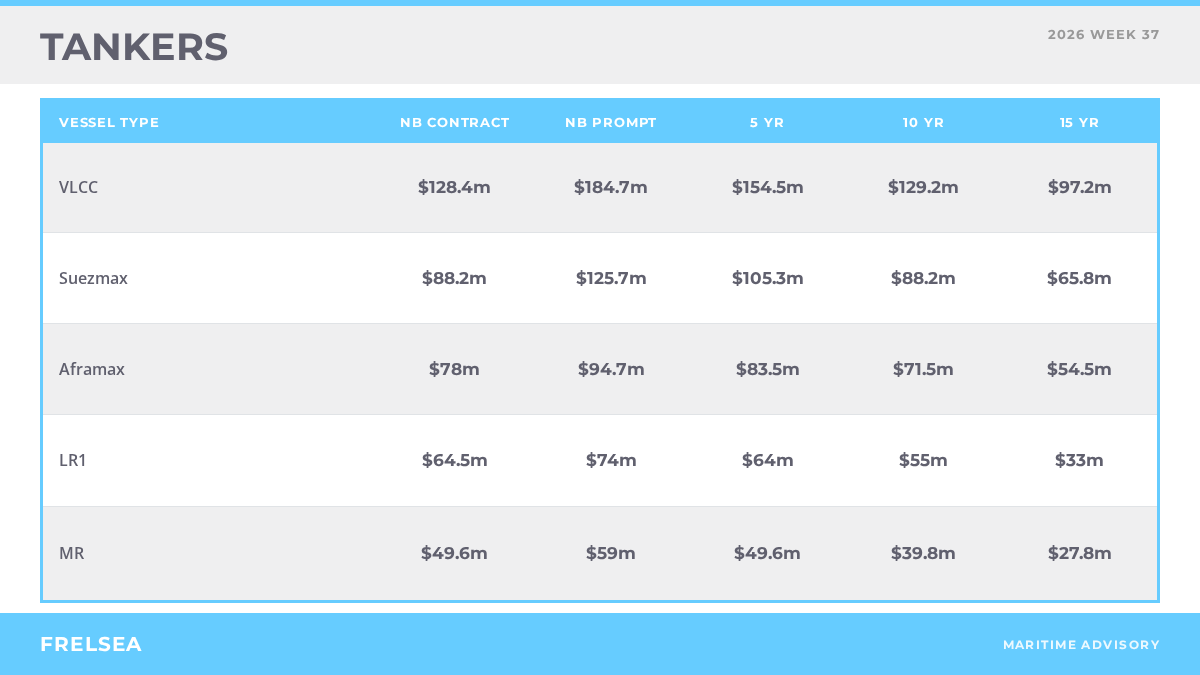
The VLCC sector carried the week. The largest commitment was the 2026-built PINIOS, 306,000 dwt and scrubber fitted, taken by Onex at USD 200 million on prompt delivery from Hengli in Dalian. Two scrubber fitted 2010-built units followed, with the KALLISTA, 317,441 dwt, reported at USD 132 million and the ASHOKA, 302,550 dwt, at USD 130 million. A year older, the NISSOS HERACLEA, 313,525 dwt, went to Middle Eastern buyers at USD 112 million, and the NORNS, 309,960 dwt from Imabari, achieved the same figure. Below that band, the 2008-built RAIN CUBIC, 319,429 dwt, was committed to UAE interests at USD 90 million, and the 2002-built TINA 5, 316,502 dwt, changed hands at USD 55 million. The weight of buying in modern tonnage follows the tonne-mile lengthening produced by rerouting around the Strait of Hormuz.
Suezmax buying stayed steady across the age curve. The 2011-built STELLA, 164,714 dwt from Hyundai Samho, was reported at USD 80 million, and the 2012-built SEAWAYS SABINE, 158,493 dwt from Samsung, went to Trafigura at USD 78 million. The 2007-built SUEZ ENCHANTED, 159,233 dwt, traded at a wide discount to both at USD 50 million. At the front of the curve, Delta Tankers took a 2027-delivery Daehan resale at USD 107 million, roughly double what a nineteen-year-old unit commands.
Product tonnage spread across sizes. Greek buyers took two coated LR2 units, the 2025-built KOS, 115,026 dwt, at USD 95 million and the 2022-built GREEN ADVENTURE, 114,319 dwt, at USD 83 million. Chinese buyers acquired the 2010-built Aframax PS AMALFI, 108,958 dwt, at USD 45 million. Four 2025-built chemical units of 18,444 dwt sold en bloc at USD 25.5 million each.
Ordering supported the product sizes. Schoeller contracted four 50,000 dwt units at Chengxi, with the first at around USD 45 million and the remaining three at about USD 42 million each for 2029 and 2030 delivery.
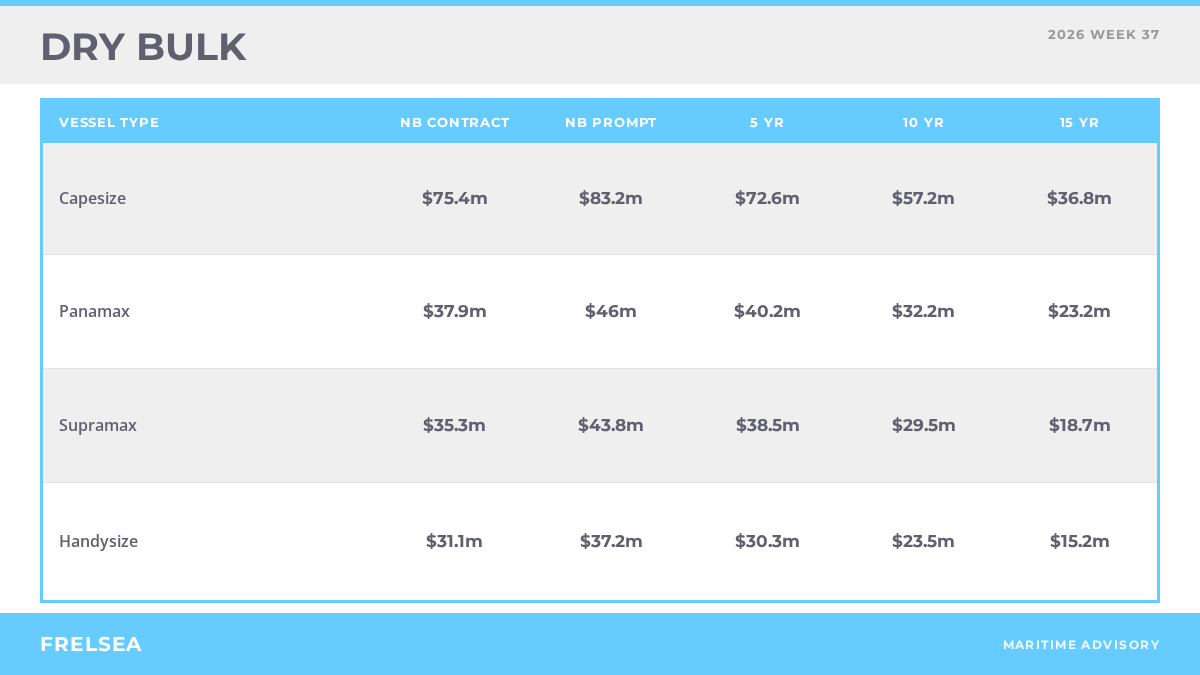
Kamsarmax buying set the tone. BW Group committed the 2019-built and scrubber fitted BW JAPAN, 81,609 dwt from Tsuneishi Cebu, to Great Eastern at USD 38.2 million. The 2016-built OSAKA STAR, 84,947 dwt from Sasebo, followed at USD 34 million, with the 2013-built DAEBO GLADSTONE, 81,399 dwt, at USD 21 million for November and December delivery and the 2012-built CK VENTURE, 82,269 dwt, at USD 19 million.
Panamax values held a tight band by age. The 2011-built DART TRADER, 79,467 dwt, was reported at USD 13.7 million with surveys due, and the 2010-built NBA VIVA, 75,026 dwt, at USD 15.5 million. Three units built between 2002 and 2007 traded from USD 7.85 million to USD 11.5 million, with the 2002-built DOLPHIN 76, 74,133 dwt, at the bottom of that range to Chinese buyers.
The geared sizes carried the most volume. A 2027-delivery Ultramax resale at Jiangsu Haitong was reported at USD 39 million, while the 2016-built OCEAN TIANBAO, 63,455 dwt, went to Turkish buyers at USD 26.5 million and the 2013-built AERIKO, 63,351 dwt, at USD 24 million. In the Supramax sector, the 2012-built SKY KNIGHT, 58,078 dwt from Shin Kurushima, achieved USD 21.5 million, the 2010-built LUZON, 55,657 dwt, USD 18.2 million and the 2012-built DESERT SPRING, 57,437 dwt, USD 17.9 million. Sea World Management sold the 2009-built scrubber fitted sisters SW NORTH WIND I and SW SOUTH WIND I, 55,989 dwt each, en bloc at USD 31.05 million.
Handysize buying favoured modern tonnage. The 2019-built open hatch WESTERN DONCASTER, 39,461 dwt, was reported at USD 24 million, and Greek interests took the 2015-built BOSTON HARMONY, 38,561 dwt, at USD 23 million and the 2015-built CRIMSON WYOMING, 33,117 dwt, at USD 18 million. Below them, the 2014-built BATMAN, 34,527 dwt, achieved USD 15.5 million.
Ordering supported the larger sizes. Wooyang Shipping placed four 210,000 dwt units at New Times at USD 108 million each against twenty-five year charters to Vale, and H-Line contracted two LNG dual fuel units of the same size at the same yard for POSCO. In containers, Yang Ming ordered six 13,650 TEU units at Hanwha Ocean at around USD 189 million each.
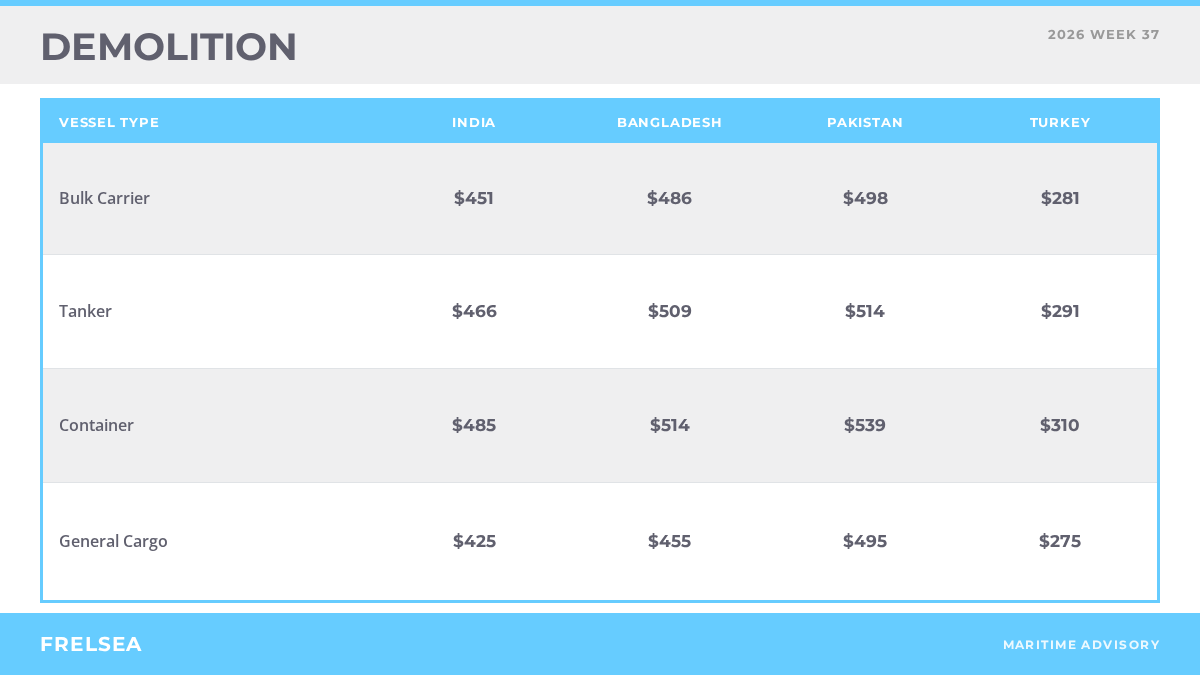
Fresh business was scarce. Three sales were reported, all to Bangladesh. The 1996-built SUN GOLD went at USD 488 per LDT over 7,596 LDT, the 1997-built UNIORDER at USD 450 per LDT on an as is Belawan basis with redelivery at Chattogram, and the 1994-built tanker V.L. 15 at an undisclosed level.
Price levels held firm despite the quiet. Pakistan continued to lead the subcontinent, bidding close to USD 500 per LDT for bulk carriers and above USD 510 for tankers, with Bangladesh a little behind and India closing the gap as domestic steel values firmed. Turkey traded near USD 280 per LDT with local plots occupied.
The constraint is unchanged. Freight earnings continue to reward keeping vintage bulk carriers in service, and secondhand values sit far above scrap levels, so yards are bidding against both daily income and asset prices. Indian yards draw structural support from the continued absence of Iranian steel imports, which leaves domestic re-rolling mills dependent on ship derived scrap. In Bangladesh, port authorities are reported to be requiring an International Ready for Recycling Certificate before issuing anchoring permission, a change expected to add time and cost for sellers.