Week 36 produced a mid-sized tanker list, a deep Handysize dry bulk book and a recycling market where price strength continued to outrun candidate supply.
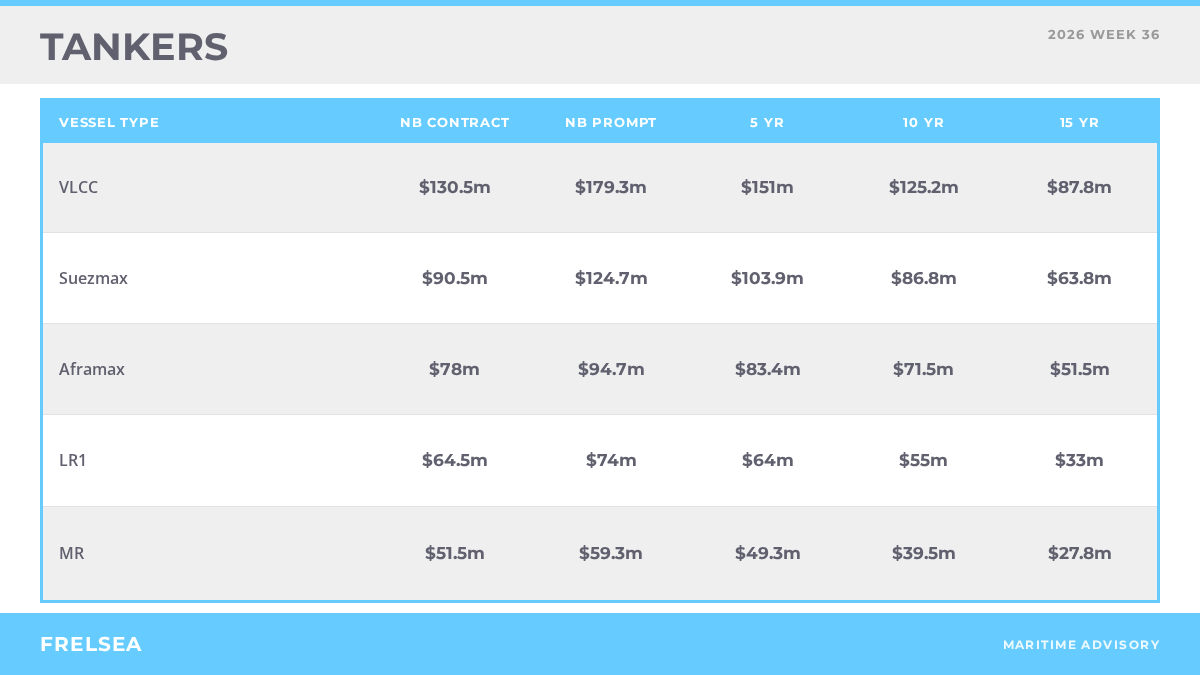
Crude activity was thin at the top of the market and concentrated below it. The 2005-built Suezmax OCEAN START, 158,280 dwt from Hyundai Heavy Industries, was reported at USD 47.4 million with a scrubber and ice class 1B notation. In the LR1 sector, Greek buyers took the 2008-built CABO SAN VICENTE, 63,605 dwt from STX Jinhae, at USD 22 million. The vessel is ice class 1A, CAP 1 rated and scrubber fitted. The 2009-built VOULA, 73,774 dwt from New Times, achieved the same figure.
Product tonnage accounted for most of the reported volume. Three 2005-built Uljanik sisters of 47,171 dwt each, the SUNDO HORN, the WINFORT and the CHAMPION CONCEPT, were each reported at USD 13 million, giving the clearest reference point of the week for twenty-year-old MR2 tonnage. Against that, the 2008-built GRAN COUVA, 47,128 dwt from Hyundai Mipo and CAP 1 rated, was committed at USD 19.25 million. Besiktas continued to build out its fleet with the 2014-built LVM AARON, 50,927 dwt from Dae Sun, at USD 35.5 million.
Smaller chemical tonnage traded steadily. Asian buyers acquired the stainless steel ORIENTAL MARGUERITE, 14,367 dwt built 2008, at USD 14.3 million, Vietnamese buyers took the 2008-built KTS BROWN at USD 10 million, and the 2006-built VULCANELLO M changed hands at USD 7.5 million.
Security conditions remain the dominant influence on crude tanker employment. Several vessels were struck in the Red Sea and around the Strait of Hormuz during the period, and Bab el Mandeb transits fell by 14 per cent in August. Owners are pricing that risk in, which tightens prompt availability and supports values for modern tonnage.
Tanker ordering stayed active. K-Line contracted three 311,000 dwt crude carriers at Nihon at USD 131 million each, Sea Pioneer placed six firm LR2 units of 115,000 dwt at SK Oceanplant at around USD 73 million, and SC Shipping exercised options on five 25,900 dwt stainless steel chemical carriers at Wuchang at about USD 44.2 million each.
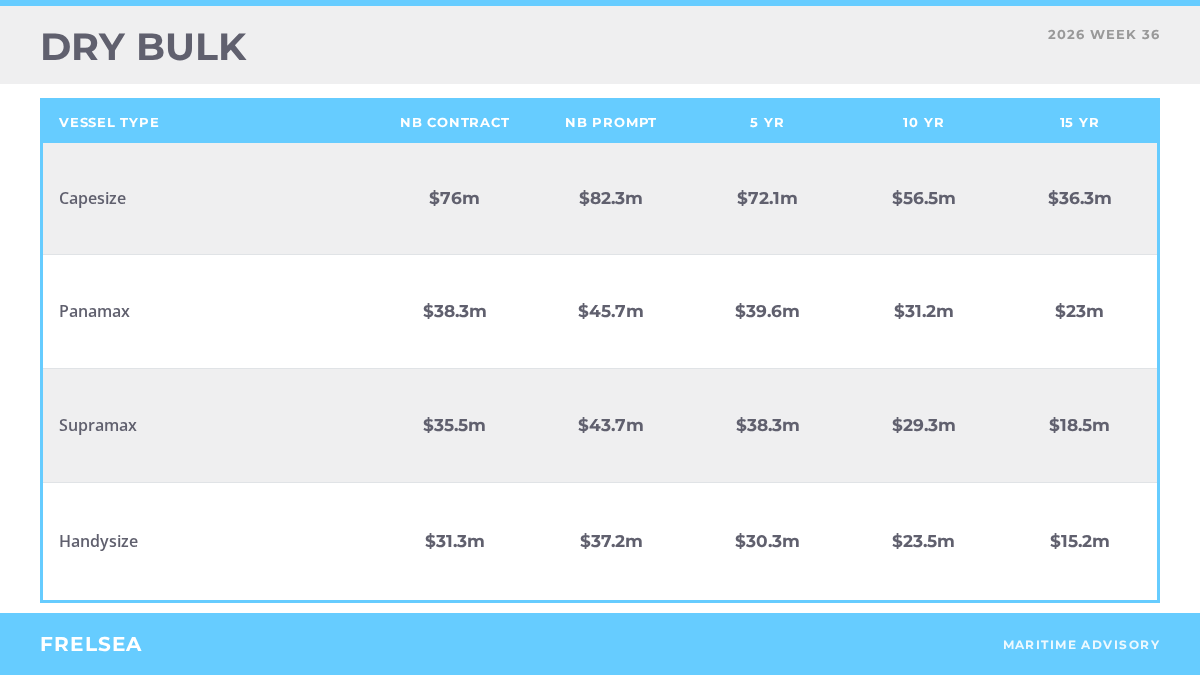
Capesize buying resumed after a quiet stretch. Lavinia Corp committed the 2010-built and scrubber fitted ERATO, 180,120 dwt from Imabari, at USD 38 million on charter free delivery in the fourth quarter. At the other end of the age curve, the 2004-built NBA PEACE, 174,766 dwt from Shanghai Waigaoqiao, was reported at USD 19 million with surveys due in early 2027.
Supramax values held a wide spread by age and condition. Greek buyers took the 2014-built eco OBE LOTUS, 55,884 dwt from Mitsui, at USD 23.2 million, the strongest price in the segment. Kawasaki Kisen Kaisha sold the 2011-built STENIA COLOSSUS, 58,731 dwt, at USD 21 million on charter free delivery in October. Older tonnage cleared well below that, with the 2006-built and scrubber fitted COLUMBIA RIVER, 55,922 dwt, at USD 13 million to Chinese buyers and its yard sister SILVER STAR, 55,725 dwt, at USD 8.6 million. The 2011-built CBW LIAN YUN GANG, 56,869 dwt, realised USD 10.5 million through an auction in Nigeria.
Handysize was the deepest segment by transaction count, with nine units reported between USD 9.3 million and USD 18.6 million. The 2014-built open hatch WOOYANG CLES, 39,202 dwt, led at USD 18.6 million, followed by the 2013-built ANSAC PRIDE, 37,094 dwt from Onomichi, at USD 18.5 million and the 2016-built IVS TEMBE, 37,735 dwt from Kanda, at USD 17.4 million. Dutch buyers took the 2013-built DEVBULK SINEM, 38,009 dwt, at USD 15.2 million. Two court sales sat at the bottom of the range, with the 2012-built BAM ARION, 30,003 dwt, going to Indian buyers at USD 9.4 million through an Admiralty auction in Rotterdam.
Container tonnage found firm bids. The 2007-built BHUDTHI BHUM, 6,310 TEU, was reported at USD 50.5 million, the 2008-built NAVIOS JASMINE, 4,730 TEU, at USD 34.5 million and the 2006-built MONACO at USD 29 million.
Ordering was heavily weighted toward boxships and large bulk carriers. Cosco placed twelve LNG dual fuel units of 21,700 TEU at SWS at USD 224 million each, and MSC contracted a further five plus five of the same size at Zhoushan Changhong. In dry bulk, CSSC ordered ten 80,000 dwt units at around USD 48.1 million each, while Shandong Marine placed two firm 325,000 dwt trifuel units at Qingdao Beihai at USD 150 million against long term charters to Vale.
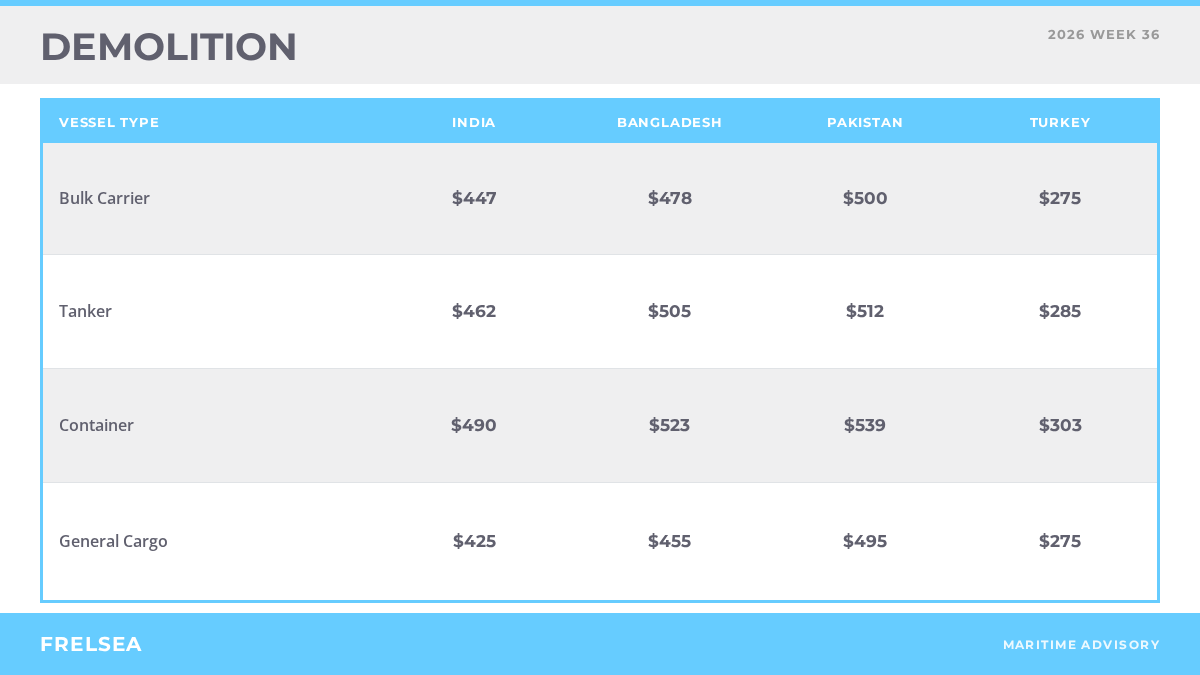
Pakistan led the subcontinent on price, taking the 1985-built PORTLAND II at USD 517 per LDT over 8,182 LDT, the 1995-built HERO SD at USD 512 per LDT and the 1997-built LARUS at USD 515 per LDT, all delivered Gadani. India improved its position with the 1996-built general cargo unit MANDARIN ARROW at USD 515 per LDT over 14,824 LDT, delivered Alang. Outside the subcontinent, the 1976-built Ro-Pax ELPIS was reported at USD 493 per LDT as is Penang.
Price strength continues to run ahead of supply. Local plate prices held firm across Alang and Gadani, and Indian yards drew support from first quarter GDP growth of 7.8 per cent and a recovering rupee. Pakistani levels eased slightly from recent highs as the most aggressive buyers filled immediate requirements. The constraint remains the freight market, where earnings reward keeping vintage tonnage in trade and leave yards bidding against both daily income and secondhand asset values. Turkish levels were flat, with plots working through existing inventory.